October 2026
Summary
▪ Multi-strategy hedge funds are premised on their ability to generate uncorrelated returns.
▪ This entails minimal correlation both to major asset classes and, importantly, to one another.
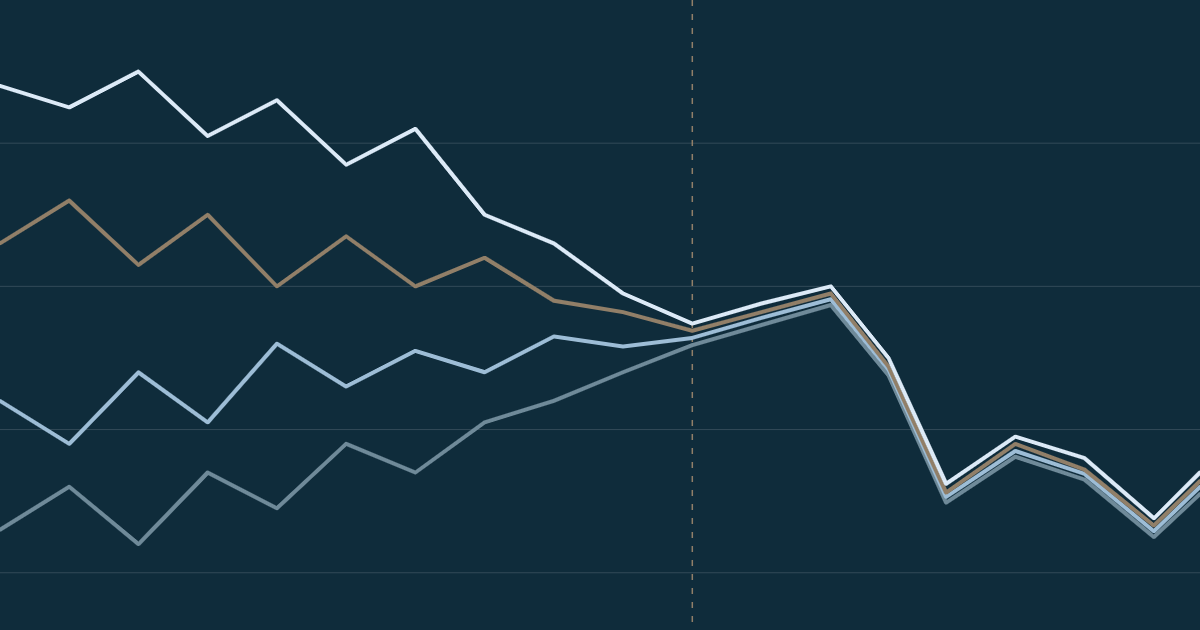
▪ However, observing the performance of a select group of four major multi-strategy funds since 2025, we notice repeated instances of correlated losses.
▪ Additionally, each such instance corresponds to a month in which either the SPY, QQQ, or both, fell sharply.
▪ Indeed, rolling correlations amongst this group of funds are presently elevated, much of which can be explained by common exposure to US equities (SPY/QQQ).
▪ However, even after accounting for shared US equity beta, more than half of the rolling correlation between funds remains unexplained.
▪ Recent research by Barclays notes an increase in cross-asset correlations (between equities, rates, credit and commodities); this might plausibly be driving changes in inter-fund correlations.