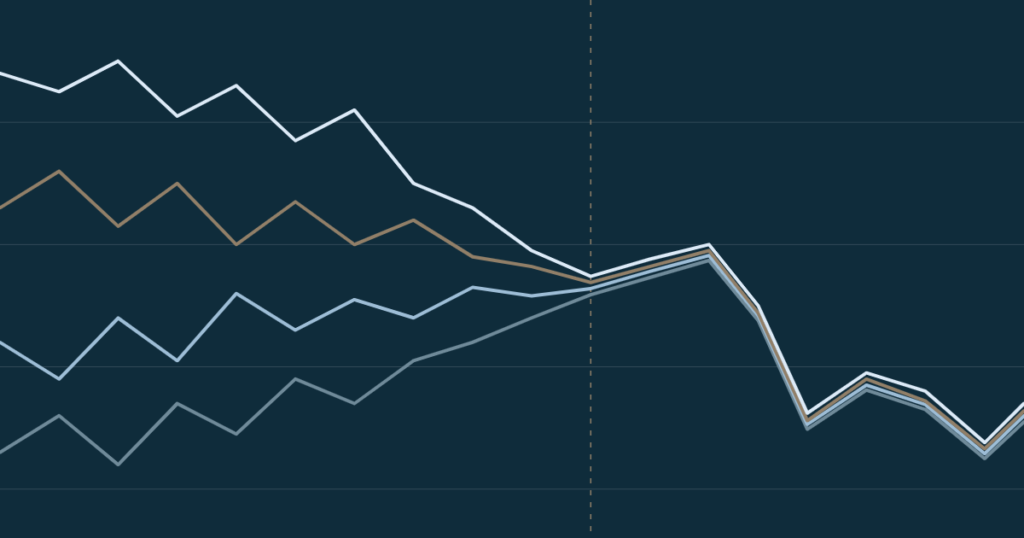
August 2026 - For the longest of times, the Federal Reserve deployed ‘forward guidance’ - the practice of giving markets clues as to how the policy rate will evolve – to ensure low volatility in interest rate markets.
Kevin Warsh, the new Fed Chair, wishes to limit the extent of this guidance. Indeed, at the most recent FOMC meeting, he argued that market participants should arrive at their own assessments of what economic data implies about the optimal policy rate – free of the Fed’s commentary. However, the effect has been to increase volatility in interest rate markets.
The yield curve is driven by two main forces, respectively the short-term interest rate and the long-term one. The first one reflects genuine, mechanical repricing of increases and decreases, whereas the latter roughly tracks the average of short-term yields over that horizon plus a term premium. The term premium is essentially an extra compensation for the risk of holding a longer maturity bond. What forward guidance does is that it shrinks the plausible outcomes that the term premium can realize. In the absence of guidance, however, the premium can move more extremely, causing uneven shifts in the yield curve. Indeed, the increase in the ‘5s30s’ curve (the difference between the 30yr and 5yr yields) upon the latest FOMC meeting was among the largest on record.
This is generating opportunities for hedge funds with macro-driven strategies, as they can monetize large moves in interest rates. Interest rates will prove more volatile, now, meaning that outright moves will be larger and so the payoff to expressing certain views will increase. In addition, because of these moves, interest rates might diverge more starkly from an estimated ‘fair value’. This creates opportunities to trade the eventual reversal of extreme moves.
The current environment promises to be a rewarding, albeit challenging, environment for macro hedge funds.